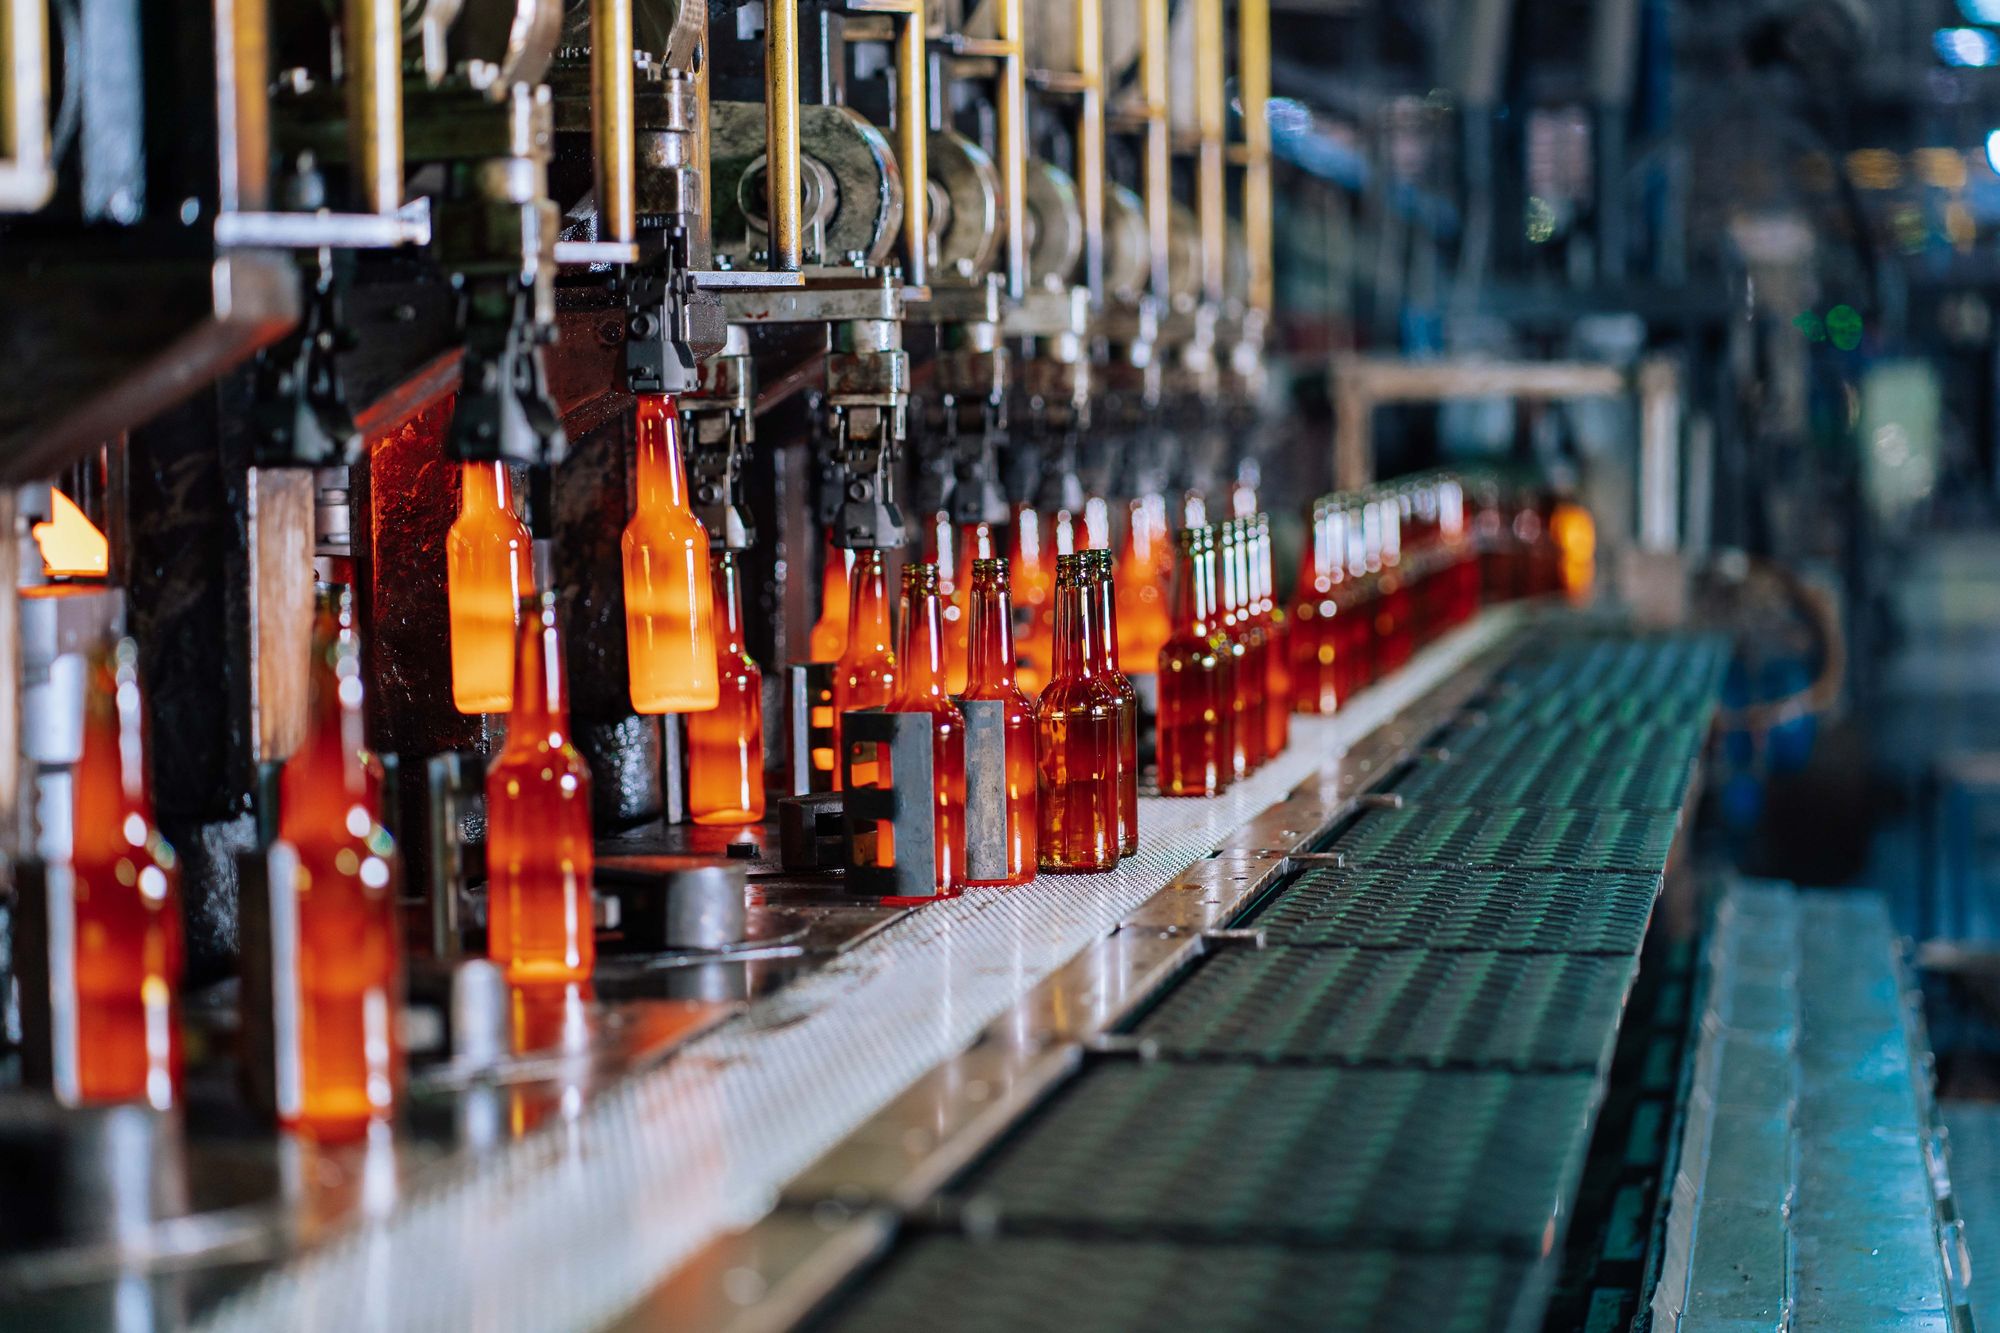
Australian manufacturers spend heavily on process improvement, new materials and production innovation, and a lot of them never claim, because the program sounds like it is meant for laboratories and software startups.
A company that systematically experiments with new processes, materials or designs to get past a technical problem is one of the strongest candidates there is. For a company turning over less than $20 million the offset is 43.5 per cent and refundable, so every $100,000 of qualifying spend returns $43,500 from the ATO, profitable or not. Prime Innovation, a specialist division of Prime Partners, works with manufacturers on identifying the activity, quantifying the spend and keeping records that hold up.
That one line settles most manufacturing questions. Work qualifies where it is experimental investigation carried out to generate new knowledge, and where the outcome cannot be known or determined in advance. Optimising within known limits, maintaining equipment, testing to a standard, and scaling up a proven process all sit outside it, however much engineering effort goes in.
Novel materials, composites or alloys where how they behave under production conditions is genuinely uncertain.
New manufacturing processes aimed at outcomes that cannot be reached by known methods.
Automated production systems where hitting the target speed, precision or reliability is technically uncertain.
New products where the design, the materials or the method of making them involves unresolved technical problems.
Systematically finding the root cause of a defect and developing a solution that takes more than standard troubleshooting.
New processes to cut environmental impact where whether the target can be met at all is an open question.
New tooling, jigs or fixtures that need experimental work to reach the performance required.
Routine quality control: standard testing, inspection and monitoring by established methods.
Optimising production within known ranges, to the manufacturer's specifications.
Maintenance and repair, routine servicing and breakdowns.
Scaling up production using a proven process with no new technical problem in it.
Compliance testing against a regulatory standard by known methods.
Installing and running proven equipment according to the manufacturer's guidelines.
Minor product variations: colour, size or cosmetic changes with no experimentation behind them.
A building products manufacturer developing a panel from recycled plastic and natural fibres, testing fibre to plastic ratios, binding agents and manufacturing temperatures against structural strength, fire resistance and weathering.
A metal fabricator experimenting with new cutting pattern algorithms and alternative tooling geometries, to take waste from 18 per cent to under 8 while holding dimensional accuracy and line speed.
A food manufacturer developing automated packaging for variable dimension products at 40 per cent faster rates. The uncertainty: whether vision-guided robotics can hit the picking accuracy and the speed at the same time.
An agricultural equipment maker developing a multi-layer coating system for harsh rural conditions, aimed at a fifteen year life under UV, chemical and mechanical stress.
Forty five employees including six in engineering, aggregated turnover $12 million. The R&D is developing a high performance polymer component to replace a metal part.
| Category | Total cost | Eligible | Why |
|---|---|---|---|
| Engineering team salaries | $520,000 | $390,000 | 75% on R&D, from timesheets |
| Production staff on trial runs | $180,000 | $54,000 | 30%, during the experimental runs |
| Raw materials | $95,000 | $95,000 | Consumed in trials only |
| Prototype tooling | $120,000 | $120,000 | Moulds for experimental components |
| External laboratory testing | $45,000 | $45,000 | Mechanical and thermal testing |
| Equipment, decline in value | $60,000 | $44,000 | 73% apportioned to R&D |
| Total | $1,020,000 | $748,000 |
$748,000 at 43.5 per cent is a refundable offset of $325,380. For a capital intensive business putting money into the next generation of its products and processes, that is a real amount of cash coming back into the year it was spent.
Illustrative only. What a claim is worth depends on your facts and your apportionment.
Manufacturing R&D is physical, which means the proof exists for a few hours on the line and then it is gone. It cannot be reconstructed afterwards from memory and a delivery docket.
That is usually where the claim is. If the answer was not obvious at the start and somebody had to try things to find it, there is a conversation worth having.
Contact Prime Innovation→Once a month we send our latest thinking on tax, business, and the moments that shape a year. Practical, considered, and written for people who would rather understand the why than chase the headline.